
Section 179D rewards commercial building owners, architects, engineers, and contractors who design buildings with Energy-Efficient Commercial Building Property (EECBP) by providing a federal tax deduction.


The deduction is changed from $0.60, $1.20 or $1.80 per sq ft to a sliding scale. Now starting at $0.54/sq. ft. for 25% energy reduction, increased by $0.02 per percentage point in energy reduction, up to $1.07/sq. ft. at 50%.
For those meeting the Prevailing Wage Requirements and Apprenticeship Requirements, the deduction now starts at $2.68 for 25% energy reduction, increased by $0.11 per percentage point in energy reduction, up to a maximum of $5.36 at 50%.
In addition to government-owned buildings, all tax-exempt entities may allocate the deduction including religious, charitable, educational, political, and Native American entities.
Future retrofit projects will be eligible for a 179D deduction again in three years for privately-owned buildings, four years for tax-exempt buildings.
The interim lighting rule will be replaced with the Qualified Retrofit Plan. Instead of comparing to the ASHRAE standard, the QRP will compare the upgraded lighting to the existing lighting.
The ASHRAE Standard is renewed as 90.1-2007 until the end of 2026, which makes certification significantly easier to achieve for the next three years.

The Department of Energy provides numerous programs for computing the 179D deduction. Carrier Hourly Analysis Program is one of the first approved programs and to this day is regularly used in the design field. Because of its widespread use, we are confident we are getting the most accurate results.
Gathering clear and concise data is important when surveying buildings. Surveys are completed so that there is no question that the energy-efficient measures designed have been installed. Our detailed surveys have found that they are supportive of an IRS Audit.

It is important to have input from professional engineers who are active in the field. Their support ensures our modeling is continuously evolving with the current market.

Your goal is to maximize your depreciation potential and cash flow. You never know what opportunities you may miss or what mistakes might cost you if left to your own devices.
A cost segregation study can deliver increased cash flow with the accelerated depreciation of real estate assets.
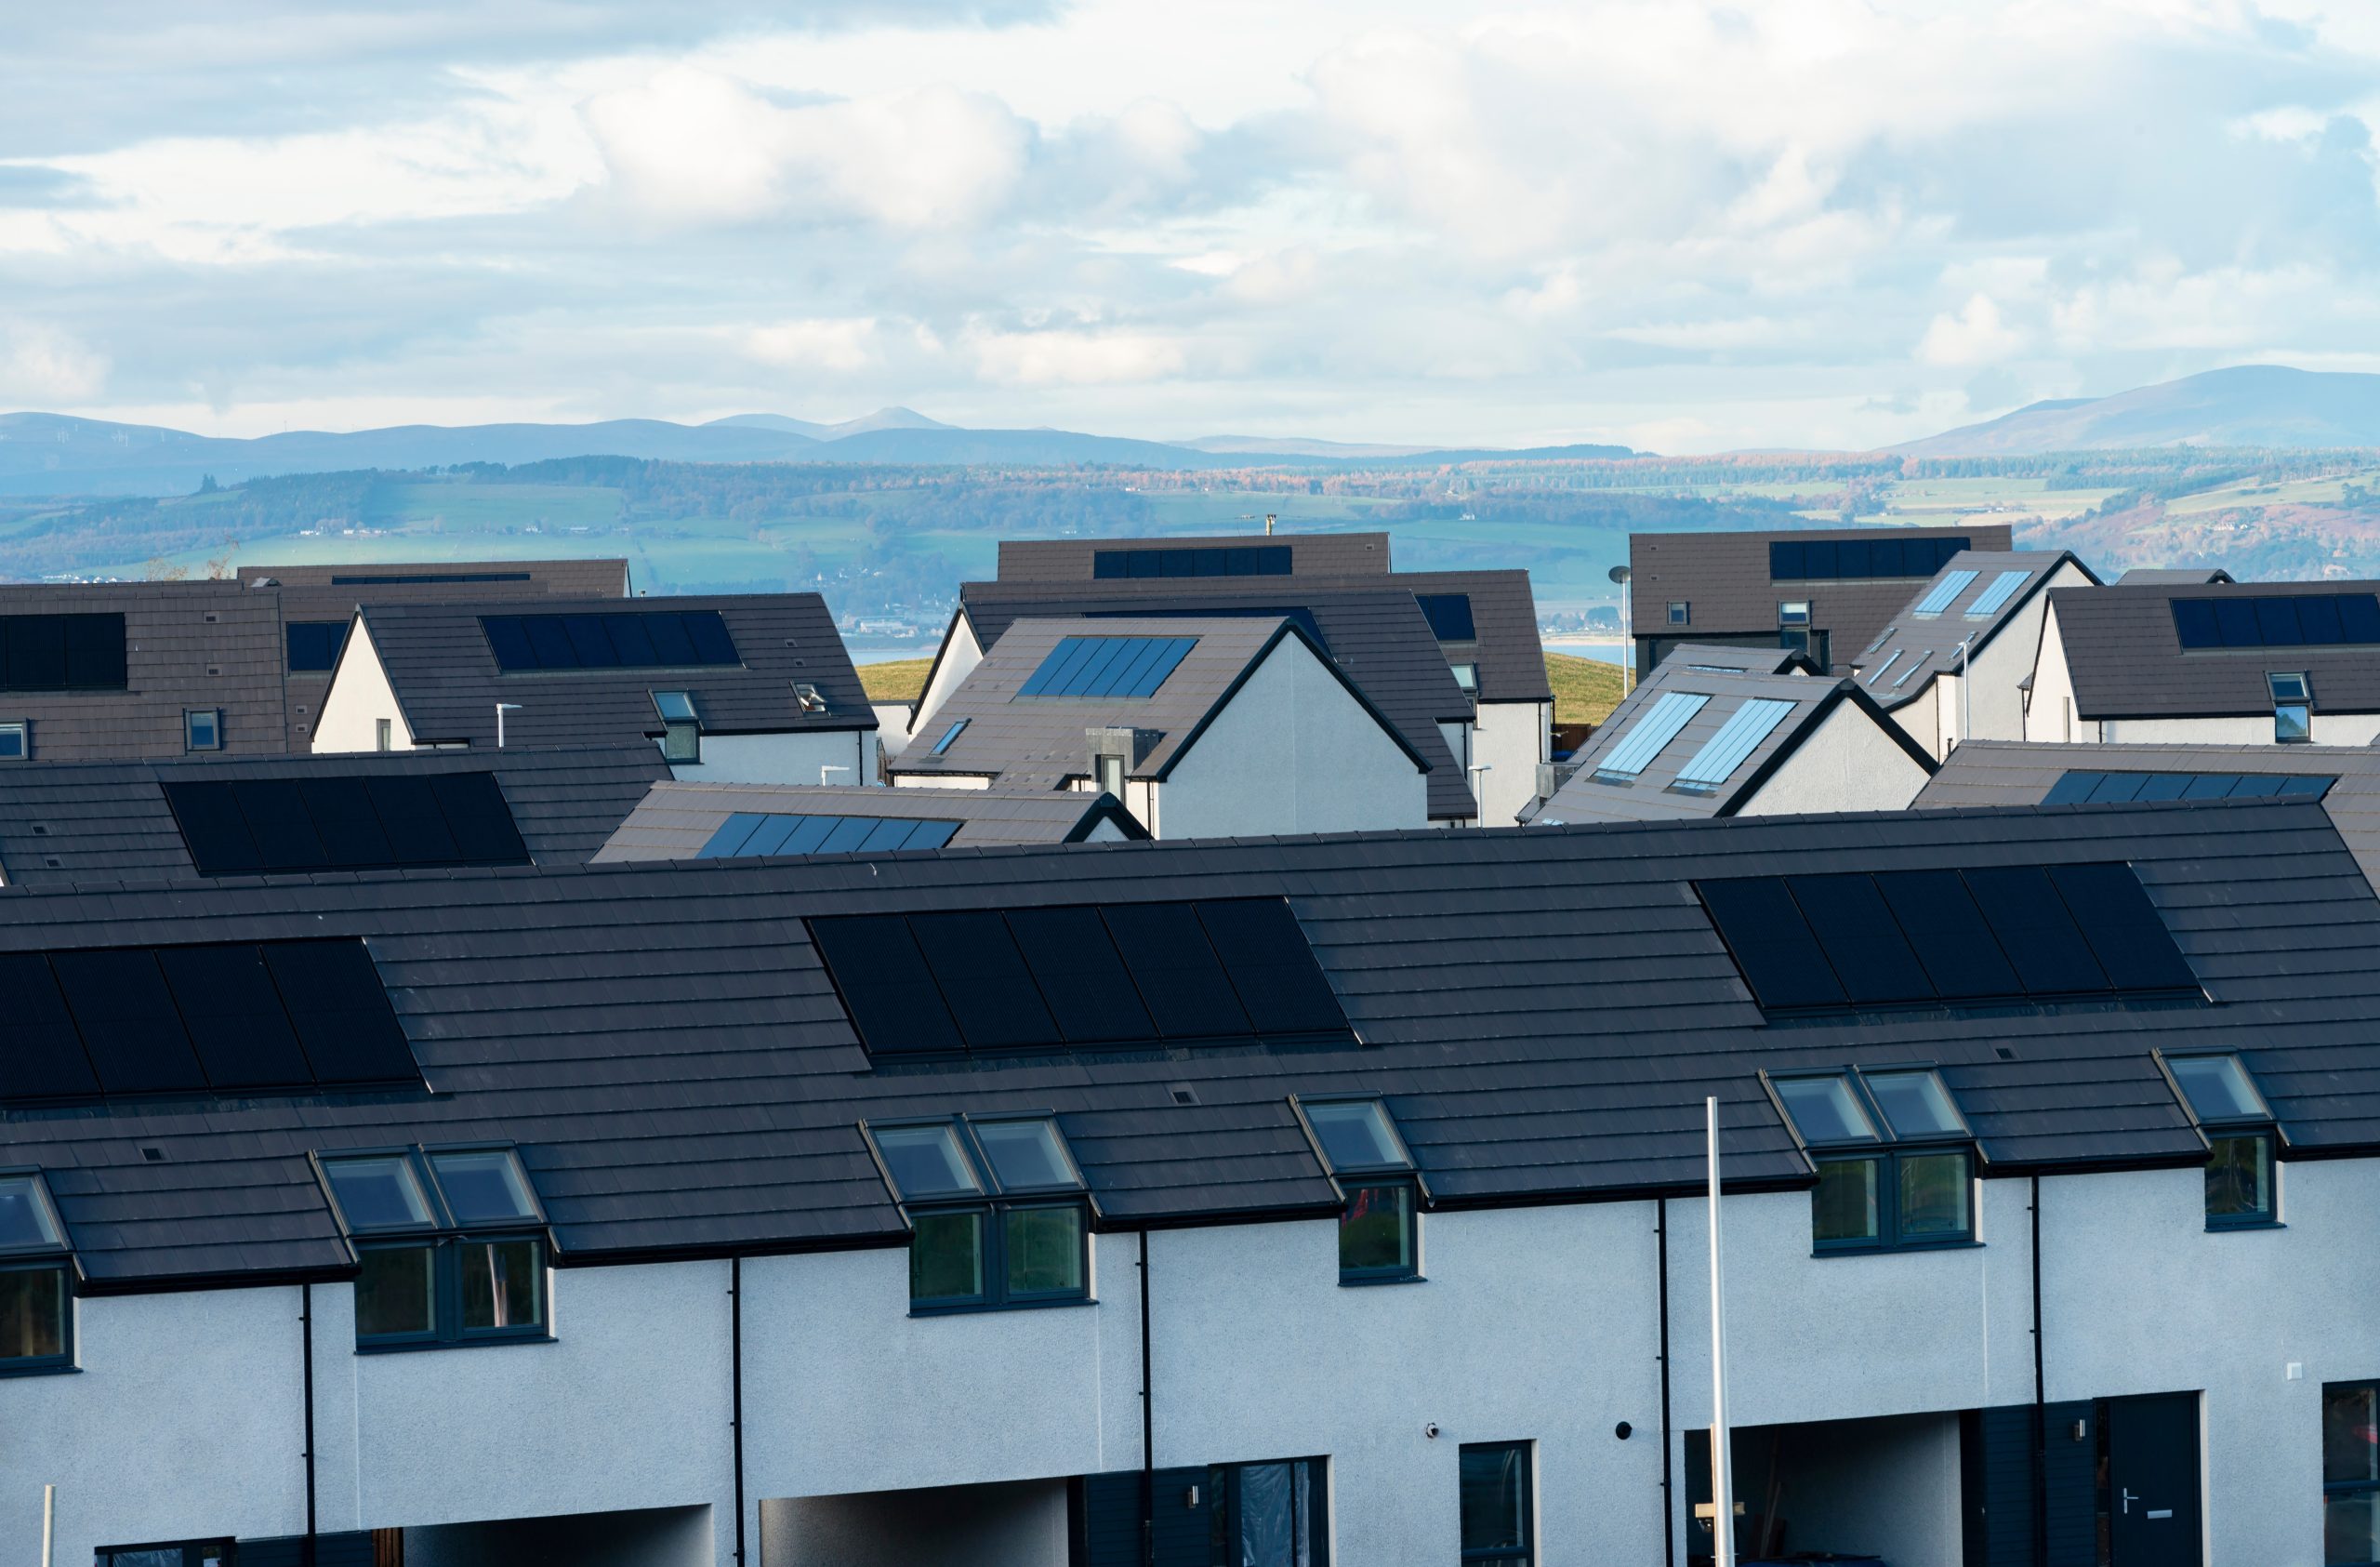
The Section 45L New Energy Efficient Home Credit rewards eligible contractors and home builders with up to a $5,000 tax credit per residential dwelling. The credit depends on eligibility requirements such as the type of home, the home’s energy efficiency and the date when someone buys or leases the home.

Section 48 Investment tax credits (ITC) are Federal tax credits for taxpayers who build facilities that generate electric power from renewable energy sources.
Reach out to a tax consultant to learn how CTI powers your business for success.
 Agriculture
 Architecture
 Assisted Living
 Construction
 Engineering
 Food & Beverage
 Hospitality
 Manufacturing
 MEP/HVAC
 Oil & Gas
 Pharmaceuticals
 Restaurants
 Retail
 Software
 Staffing
 Winery/ Vineyard