
Under the Inflation Reduction Act of 2022, to qualify for increased tax credit or deduction amounts of certain clean energy tax incentives, taxpayers generally need to:
By meeting Prevailing Wage and Apprenticeship (PW&A), taxpayers can increase the base amounts of these incentives by 5 times.
* Prevailing Wage ONLY
Coupling PW&A compliance with the IRA Energy Incentives can increase the credit or deduction by five times. Under Section 48 ITC, a total project cost of $1,000,000 would normally result in a 6% credit of $60,000. Meeting the PW&A requirements, however, will increase this credit to 30%, or $300,000.

CTI provides an end-to-end solution to streamline efficiency and ensure accuracy.
CTI interprets IRS guidance and regulations to ensure proper treatment.
CTI consistently monitors compliance throughout the project to minimize penalties.
CTI assists with pre-construction planning and best practice communication with key stakeholders and contractors.
The 179D Energy Efficient Commercial Buildings Deduction can provide building owners, architects, and engineers with up to $5.36 per square foot for improving the energy efficiency of new buildings and retrofit projects.
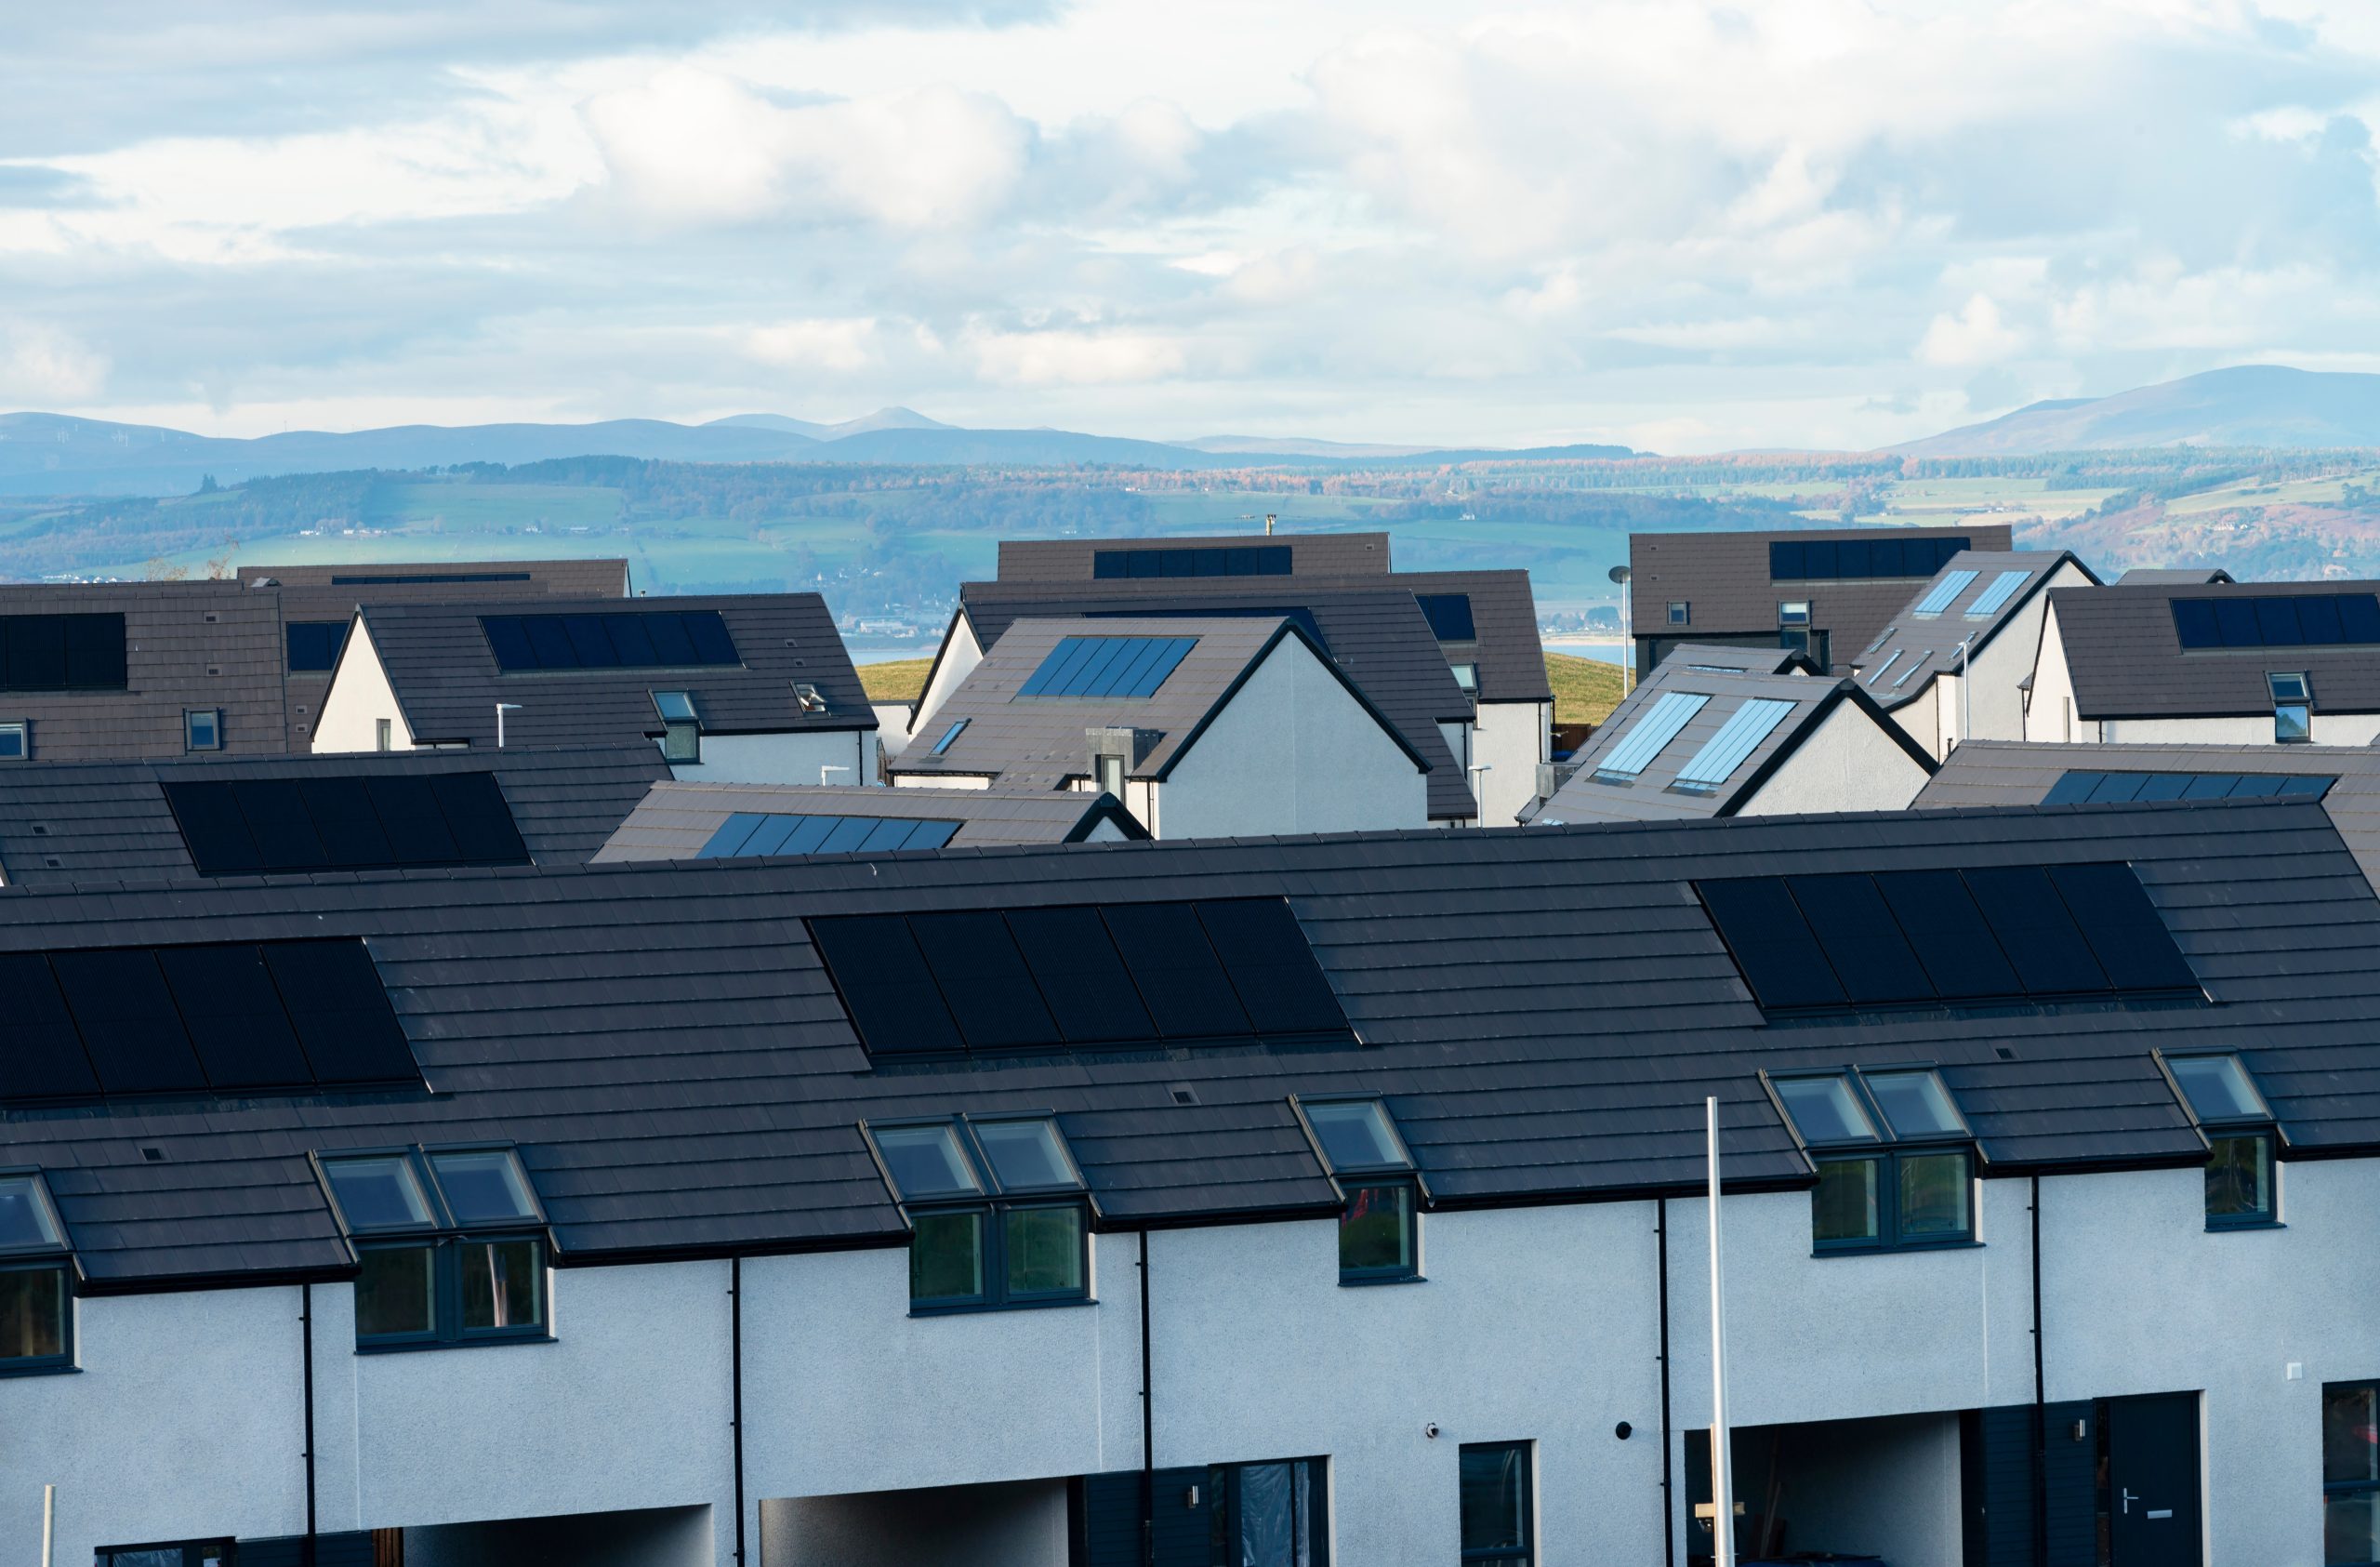
The Section 45L New Energy Efficient Home Credit rewards eligible contractors and home builders with up to a $5,000 tax credit per residential dwelling. The credit depends on eligibility requirements such as the type of home, the home’s energy efficiency and the date when someone buys or leases the home.

Section 48 Investment tax credits (ITC) are Federal tax credits for taxpayers who build facilities that generate electric power from renewable energy sources.
Reach out to a tax consultant to learn how CTI powers your business for success.
 Agriculture
 Architecture
 Assisted Living
 Construction
 Engineering
 Food & Beverage
 Hospitality
 Manufacturing
 MEP/HVAC
 Oil & Gas
 Pharmaceuticals
 Restaurants
 Retail
 Software
 Staffing
 Winery/ Vineyard

